
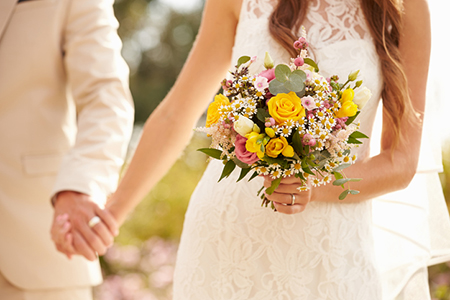
Pros and Cons of Wedding Insurance
Rain, the bride falling into a pool, a wedding cake falling over, and deposit money that’s lost because the venue went out of business a week ago.
What do all of these have in common? They’re all things that can go wrong at a wedding that can be covered by wedding insurance.
Some problems can’t be fixed with money, but this type of insurance — also called special event insurance — can provide financial protection if a wedding has to be put off due to bad weather, natural disasters, death, illness or serious injury to key participants.
Insurance riders can also be added to the policy, covering things such as crashing cakes, a guest slipping and falling, or gifts were stolen.
Medical coverage can also be added to pay the medical expenses of anyone injured at a wedding. Also, personal liability coverage can be added to cover bodily injury or property damage caused by an accident during the wedding.
Wedding insurance prices range from $125 to $550 or so, depending on coverage. Policies usually have a specified maximum amount for each area covered, and a deductible applies.
The company WedSafe, for example, offers minimal coverage of $7,500, providing up to $1,000 for problems with photos, and $500 for professional counseling.
There are some things, however, that wedding insurance is unlikely to cover. Wedding rings may be covered, but an engagement ring probably won’t be covered by insurance.
Wedding insurance also doesn’t cover a change of heart by the bride or groom. If either person gets cold feet, you’re both out of luck — financially and otherwise.
The good news is that you may not need wedding insurance if you or the site you’re having the wedding at has enough insurance. Rental halls and other sites often have their own liability insurance, though they may require couples to have additional insurance.
Your homeowner’s insurance may cover you for liability if the wedding is taking place at your home, and it may cover losses away from home if you buy a rider.
Credit cards used to buy food for the reception, for example, may reimburse you if the food doesn’t arrive. Auto insurance should cover any wedding day accidents. Trip insurance can cover a honeymoon.
I hope you found this information helpful. Please contact me for all your real estate information needs today!
 We do not attempt to independently verify the currency, completeness, accuracy or authenticity of the data contained herein. Data may be subject to transcription and transmission errors. Accordingly, the data is provided on an "as is" "as available" basis only and may not reflect all real estate activity in the market. © 2026 REsides, Inc. All rights reserved. Certain information contained herein is derived from information which is the licensed property of, and copyrighted by, REsides, Inc.
 Copyright ©2026 Lowcountry Regional Multiple Listing Service. Information is deemed reliable but not guaranteed. Information is provided exclusively for the consumer's personal, non-commercial use, and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Last Updated: September 23, 2026 10:33 AM UTC
