
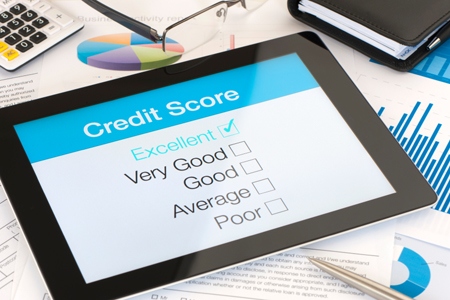
6 Small and Easy Steps to Improve Your Credit Score
The best way to improve your credit score is simple, but not always that easy: Reduce your debt.
Paying off your credit cards, or at least paying them down substantially, will not only increase your credit score, but having less debt will probably be more satisfying than a great credit score. And not using your credit cards anymore and paying off the balances is easier said than done.
But there are smaller, easier steps that can improve a credit score. Here are six:
Set payment reminders: Making credit payments on time is one of the best ways to improve your credit score. Set payment reminders on your phone or whatever calendar you use, and check if your bank offers online reminders through email or text messages.
Don’t open new accounts: If you have a short credit history, then opening a lot of credit accounts too rapidly will lower your average account age and can drop your scores if you don’t have a lot of other credit information.
Fix errors: Get a copy of your credit report and check it for errors. These can include accounts that are listed as open but closed, incorrect late payments and wrong personal information, such as your birthday. If you find any credit report errors, fix them online with the credit reporting agencies.
Don’t move debt around: How much you owe accounts for 30 percent of a FICO credit score, one of the most common types of credit score. It can be tempting to pay off one credit card with another, but that type of shell game can hurt a credit score. Instead, pay down the debt and have fewer open accounts.
Don’t max out: Stay away from hitting the top of your credit limit on your credit cards so that your credit utilization level is low. Credit utilization is the amount of your credit card balance relative to your credit limit. The higher it is, the worse it can affect your credit score.
This may be easier said than done, but keeping balances to 30 percent or less of your credit limits will improve a credit score just as much as paying your credit bills on time will.
Pay your bills twice a month: This is easier than you think and can be done with the same amount of money you were going to pay for the full month anyway.
If you’re paying down a credit card with $500 per month, for example, pay half of it just before the statement closing date and the second payment just before the due date. The first will reduce the balance that credit bureaus see and the second will ensure you won’t pay a late fee.


 We do not attempt to independently verify the currency, completeness, accuracy or authenticity of the data contained herein. Data may be subject to transcription and transmission errors. Accordingly, the data is provided on an "as is" "as available" basis only and may not reflect all real estate activity in the market. © 2026 REsides, Inc. All rights reserved. Certain information contained herein is derived from information which is the licensed property of, and copyrighted by, REsides, Inc.
 Copyright ©2026 Lowcountry Regional Multiple Listing Service. Information is deemed reliable but not guaranteed. Information is provided exclusively for the consumer's personal, non-commercial use, and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Last Updated: September 23, 2026 10:33 AM UTC
